
Buying a home, refinancing a mortgage, or deciding what to do with the equity in your current home can feel complicated—especially when interest rates and home prices dominate the headlines.
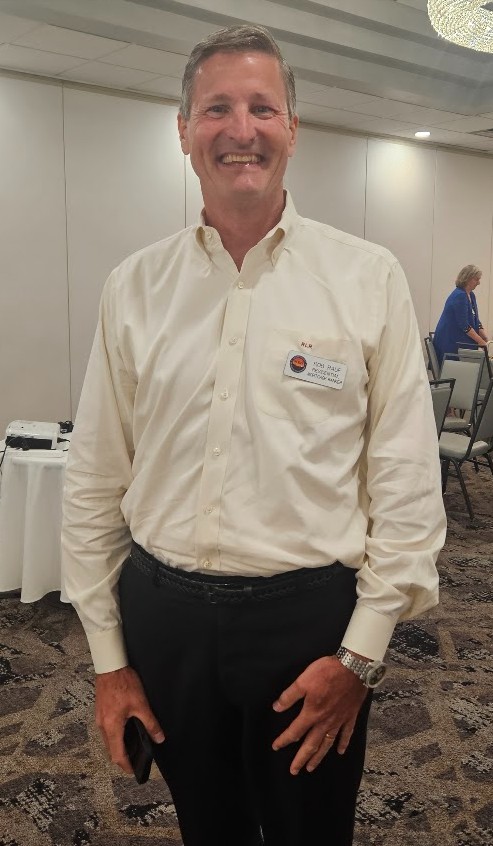
During a recent OCBA Commercial Craft Talk, Rob Rauf of CMG Home Loans shared insights from nearly 40 years in the mortgage industry. His presentation focused on helping consumers look beyond a single interest rate and understand the bigger financial picture when making decisions about their homes.
There Is No Single “Mortgage Rate”
One of the first things borrowers should understand is that there isn’t one mortgage rate that applies to everyone.
The rate available to an individual borrower can be affected by credit score, down payment, loan amount, property details, loan program, and other factors. That makes it difficult to compare financing based solely on a rate seen online or advertised by a lender.
A more useful approach is to look at the complete loan: the interest rate, monthly payment, closing costs, loan structure, and how long you realistically expect to keep the mortgage.
The right financing strategy depends on the borrower, not simply the rate being advertised that day.
Mortgage Rates Are Influenced by a Much Bigger Market
Consumers often hear about interest rates rising or falling without much explanation about why.
Mortgage rates are connected to a much larger financial system. Inflation expectations, energy prices, economic conditions, global events, and financial markets can all influence the cost of borrowing.
Mortgages themselves are also part of a secondary market. After loans are originated, they can be pooled and sold to investors, helping provide lenders with the liquidity needed to continue making new loans.
Understanding this helps explain why mortgage rates can move even when nothing has changed about an individual borrower’s finances.
Higher Rates Haven’t Eliminated Housing Demand
Mortgage rates may be considerably higher than the historic lows consumers became accustomed to, but people still need homes.
In Ocean County and throughout New Jersey, limited housing supply continues to play an important role in home prices. There is only so much available land for new construction, while families continue to form, people relocate, and buyers move into New Jersey from other areas.
During the presentation, national housing forecasts were discussed that anticipate continued home-price appreciation over the coming years. Ocean County has also experienced strong appreciation in many communities, although results vary considerably by town and property type.
For buyers, that creates an important consideration: waiting for a lower mortgage rate doesn’t necessarily mean the home itself will become less expensive.
A 30-Year Fixed Mortgage Isn’t the Only Option
Higher fixed rates have also led some borrowers to take another look at adjustable-rate mortgages.
Longer-term adjustable-rate products can sometimes offer a lower initial rate than a traditional 30-year fixed mortgage. A seven- or ten-year adjustable-rate mortgage, for example, keeps the initial rate fixed for a substantial period before it can adjust.
That doesn’t make an adjustable-rate mortgage the right choice for every buyer. It does illustrate why borrowers should explore their options rather than assuming every purchase should automatically use the same type of loan.
How long you expect to own the home matters. Many mortgages don’t remain in place for their full term because homeowners eventually move, sell, or refinance.
Don’t Let a Low Mortgage Rate Make Every Decision for You
One of the biggest challenges in today’s housing market is the number of homeowners holding mortgages with very low rates.
Giving up a 3% or 4% mortgage can be difficult to accept. But life doesn’t stand still because someone has a great interest rate.
Families grow. Housing needs change. Jobs change. Relationships and financial circumstances change. A house that worked five years ago may no longer work today.
That makes it important to consider quality of life alongside the interest rate.
A homeowner may ultimately decide that staying put makes the most sense. Another may discover that accumulated equity makes moving more practical than expected. The important thing is to understand the numbers before assuming a low mortgage rate means you have no good options.
Your Home Equity May Be More Useful Than You Realize
Rising home values have also left many homeowners with substantial equity.
At the same time, some households are carrying credit-card balances and other debts with interest rates approaching 30%.
That difference can create opportunities worth exploring.
For some homeowners, using home equity as part of a debt-consolidation strategy may improve monthly cash flow. A new mortgage could carry a higher rate than the homeowner’s existing first mortgage while still reducing the total amount being paid each month across mortgages, credit cards, and other debts.
That doesn’t mean replacing unsecured debt with debt secured by your home is automatically a good idea. It means the decision deserves a complete financial analysis.
Instead of asking only, “What will happen to my mortgage payment?”, it can be more useful to ask, “What happens to my total monthly obligations?”
Think Long Term When Buying a Home
A home generally shouldn’t be viewed as a short-term transaction.
Buying and then selling again within a year can make it difficult to overcome closing costs and other expenses, even in an appreciating market. A longer ownership horizon gives buyers more time to build equity and absorb the costs associated with purchasing and eventually selling a property.
This is another reason financing decisions should begin with the borrower’s plans.
How long do you expect to live there? Is the property likely to meet your needs for several years? What monthly payment fits comfortably within your budget? How would a change in income or expenses affect you?
Those questions can be just as important as the interest rate.
Start With the Numbers, Not the Headlines
The biggest takeaway for consumers is that mortgage decisions are personal.
A national story about interest rates can’t tell you if you should buy a house. An online rate advertisement can’t tell you which loan program fits your situation. And having a low mortgage rate today doesn’t automatically mean moving, refinancing, or accessing equity should be off the table.
The better approach is to understand your complete financial situation and run the numbers before making a decision.
If you’re considering buying a home, moving, refinancing, or using the equity you’ve built in your property, OCBA member Rob Rauf of CMG Home Loans can help you understand the available options and how they apply to your specific circumstances.
With nearly four decades of mortgage experience, Rob can help borrowers evaluate the numbers, understand the tradeoffs, and make a more informed decision about their next step.
Call 732-740-0175 to Connect with Rob Rauf at CMG Home Loans to discuss your home financing needs and find out what options may be available to you.
Learn From Local Experts at OCBA
OCBA Commercial Craft Talks give members an opportunity to share practical knowledge from their industries while helping fellow members make better referrals and become more informed consumers.
Interested in connecting with experienced local business professionals like Rob? Request a guest ticket to an upcoming Ocean County Business Association networking lunch and see what OCBA is all about.